The Directorate General of Taxes (DGT) continues to strengthen Indonesia’s tax compliance framework through enhanced monitoring mechanisms. One of the latest developments is the issuance of Minister of Finance Regulation No. 111/PMK.03/2025 (“PMK 111”), which provides a stronger legal basis for tax compliance monitoring activities conducted by the Indonesian tax authority.
Under PMK 111, taxpayers may receive tax monitoring letters as part of the DGT’s efforts to ensure ongoing compliance. These letters are not tax audits or examinations. However, they indicate closer attention by the tax authority to a taxpayer’s reporting, payment patterns, and overall tax behaviour. Taxpayers are therefore encouraged to take proactive steps to prepare themselves—even before any monitoring letter is received.
Understanding Tax Monitoring Letters
Tax monitoring letters form part of the DGT’s preventive and persuasive approach to tax compliance. Their primary objective is to remind and encourage taxpayers to fulfil their tax obligations correctly, completely, and on time.
In line with the increasing use of digital tax administration systems such as Coretax, tax monitoring letters may now be delivered electronically, including through registered email addresses. While this improves administrative efficiency, it also increases the risk that such notices may be overlooked if taxpayers are not vigilant. Failure to respond appropriately or in a timely manner may result in escalation to more formal compliance actions.
Deadlines to respond
Taxpayers should be aware of the response deadlines applicable to different types of tax monitoring correspondence issued by the DGT.
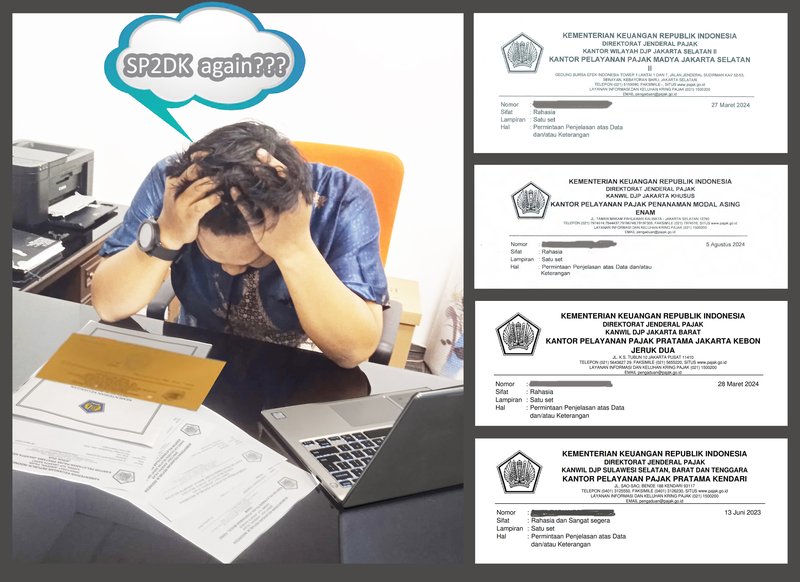
- SP2DK (Request for Explanation of Data and/or Information)
Under this PMK, taxpayers are required to respond within:
● 14 calendar days from the date of receipt; and
● An additional 7 calendar days through request for extension.
It is important to note that these timeframes are calculated based on calendar days (not working days). Weekends and public holidays are therefore included in the calculation. If a deadline falls on a public holiday, submission is typically allowed on the next working day in accordance with general administrative practice.
Given the relatively short timeframe, preparation and internal coordination are essential. SP2DK often serves as a preliminary stage before further compliance actions. - Surat Imbauan (Advisory Letter)
For advisory letters, taxpayers are typically expected to provide clarification or take corrective action within:
● 14 calendar days from the date of receipt, without any additional extension period.
● Although advisory letters are persuasive in nature, failure to respond adequately may increase the likelihood of follow-up measures by the tax authority.
To strengthen preparedness under PMK 111, taxpayers should consider the following practical measures:
- Organize financial data and supporting documents
Ensure that financial records and supporting documents are properly stored, systematically organized, and easily retrievable - For corporate taxpayers, prepare equalization working papers
Corporate taxpayers should prepare equalization working papers reconciling:
● withholding and income tax (PPh Pot/Put), and
● value added tax (VAT / PPN).
As a best practice, these working papers should be completed within two (2) months after the Corporate Income Tax Return is filed. - Maintain a competent internal tax and accounting team
A capable internal team with adequate tax and accounting knowledge, as well as a good understanding of business processes, is essential to ensure accurate and timely responses. - For individual taxpayers, prepare your tax returns based on actual data/documents Individual taxpayers should base the reporting of their incomes, assets, and liabilities on the numbers stated in actual data/documents, not only from memory (“Seingat saya....” “As far as I remember....”). Be detail on the information you provide on your assets and liabilities.
- Regularly monitor registered communication channels
Taxpayers should routinely check email addresses registered in DJP Online and Coretax, ideally at least once every two (2) days, as monitoring letters may be delivered electronically. - Ensure prompt handling of correspondence
Internal procedures should be in place to ensure that any correspondence from the DGT is immediately communicated to responsible personnel. - Engage a tax advisor in advance, if needed
If professional assistance may be required, taxpayers are encouraged to identify and engage a qualified tax consultant before receiving any monitoring letter, allowing sufficient time for preparation and strategy.
PMK 111 complements existing technical guidelines, that is SE-05/PJ/2022, and signals continued regulatory development with greater emphasis on taxpayer oversight. By strengthening documentation, internal capabilities, and communication readiness, taxpayers can confidently face tax monitoring processes and reduce compliance risks.
Are you ready for the new era of tax monitoring under PMK 111?
Read more :
- PMK 111-2025 - ENG
- PMK 111-2025 - IND
Attachments :
- PMK 111 Tahun 2025 Pengawasan Kepatuhan Wajib Pajak
- DGT PPT - PMK 111 Tahun 2025 Pengawasan Kepatuhan Wajib Pajak